You open your banking app and notice that your credit score has dropped by 12 points. There has been no missed payment, new loan or collection notice, so the change seems to come from nowhere.
Before you worry, it helps to know what the number actually is. For example, a credit score is not stored on your card, and there is no single score that every lender sees. Instead, a scoring model calculates a prediction from one of your credit reports at a specific moment. So when a lender reports a new balance, an account gets older or an application appears, the number can move. In other words, a change of a few points does not always mean something important happened.
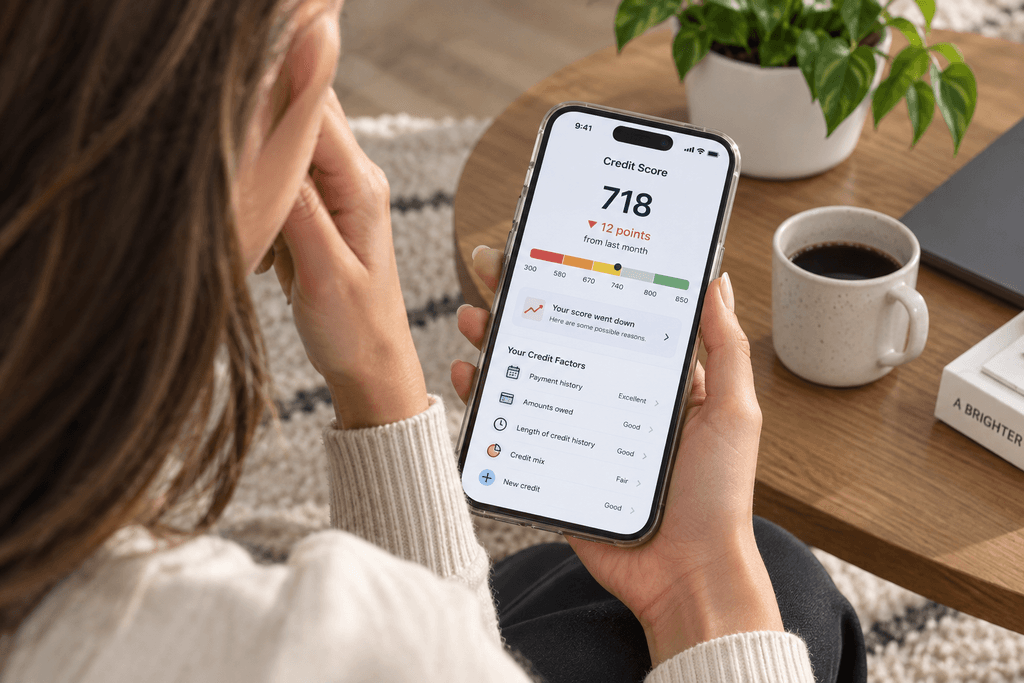
What a credit score actually predicts
In short, a credit score is a number that predicts how likely you are to repay credit on time. According to the CFPB, most scores range from 300 to 850, although not every model uses the same range. For reference, the average U.S. FICO Score was 714 in 2026, according to FICO’s Credit Insights report.
Lenders may use your score to decide whether to approve a mortgage, car loan or credit card, and what rate or limit to offer. In some cases, it can also matter for renting a home or for insurance, depending on the law. However, the score does not make the whole decision. A lender may also look at your income, job, current debts and its own rules.
Most importantly, the score does not measure your income, savings, intelligence or worth as a person. Instead, it answers a much narrower question about credit risk, using the data and the model chosen for that calculation.
MONEY TRAPA number that feels like a grade
“My score dropped 12 points. Something is wrong with me or my finances.”
A credit score is a prediction from one credit report on one day, so small changes are normal. Often, they come from a routine balance update, not a real problem.
Why a three-digit number can feel like a verdict
A score looks exact and objective, so it is easy to treat it as a grade on your whole financial life. A drop can feel embarrassing, while a high number can bring pride or even overconfidence. Yet the model does not know why a balance exists, whether you had an emergency or how much you have in savings.
Misunderstandings are very common. In FICO’s Fall 2026 Credit Insights report, more than 1 in 4 Americans (27%) believed that checking their own score lowers it. In addition, nearly two-thirds (65%) either believed income is part of the score or were not sure. Neither is true.

When the score becomes the goal
Once you learn the scoring factors, it is tempting to play the game: carry a balance to “show activity”, take out a loan for credit mix or rush to open a new card after a drop. Economists describe this problem with Goodhart’s law: when a measure becomes a target, it stops being a good measure. At that point, the score starts to control the behavior it was supposed to describe, often at a real cost in interest and fees.
Therefore, a healthier approach is to treat your score like a warning light on a car dashboard. It tells you something may be worth checking, but it does not describe the whole condition of the vehicle. So when the number changes, first look at what changed in your report, and only then decide whether any action would improve your actual finances.
Where the number comes from
In the United States, several organizations are involved. To begin with, banks, card issuers and other lenders may send account information to the three nationwide credit bureaus: Equifax, Experian and TransUnion. Then each bureau organizes that information into a credit report, and finally a scoring model uses one report to calculate a score.
| Participant | Role |
|---|---|
| Lender or card issuer | May send account information to one or more bureaus |
| Credit bureau | Puts the information together in a credit report |
| Scoring company (FICO or VantageScore) | Calculates a score from one report |
| Lender reviewing an application | Looks at the score along with other criteria |
Based on the CFPB’s explanation of credit reports and scores.
As the CFPB explains, lenders are not required to report to every bureau, which is one reason your three reports may not match. Also, if you want the bigger picture of how borrowing works, start with What Is Credit and How Does It Work?
Why you have more than one credit score
In fact, there is no single, permanent score attached to your name. Instead, your score can change depending on three things:
- The report. A score based on your Equifax report may not match one based on Experian or TransUnion, for example if a lender updated one bureau before another.
- The model. FICO and VantageScore are two different brands, and each has several versions. Some versions are designed for specific types of lending, such as car loans or mortgages.
- The date. A score reflects the information available on the day it was calculated, so two apps updated on different days can show different numbers.
As a result, the free score in your app may be different from the one a lender sees, and neither one is necessarily wrong. For everyday monitoring, the overall health of your reports matters more than making every app show the same number.
What affects a typical FICO Score
FICO publishes five broad categories and their approximate weight for the general population, as explained in What’s in my FICO Score:
| Factor | Approximate weight | What it looks at |
|---|---|---|
| Payment history | 35% | Whether you paid on time, how late and how recently |
| Amounts owed | 30% | Balances and how much of your credit limits you use |
| Length of credit history | 15% | How old your accounts are |
| New credit | 10% | Recent applications and new accounts |
| Credit mix | 10% | Experience with different types of credit |
Source: FICO. The weights vary from person to person, so they are not a points calculator.
Payment history is the largest category. For that reason, paying every required amount on time is the foundation of a good score. Even so, no one can honestly promise that one late payment will cost every person the same number of points.
Amounts owed includes how much of your available credit you are using, known as credit utilization. For example, we explain it step by step, with a calculator, in How Credit Utilization Works.
Length of credit history rewards time, so it cannot be rushed. In fact, opening several accounts to speed things up can backfire, because new accounts lower the average age of your file.
New credit looks at recent applications. When you apply, the lender usually makes a hard inquiry. However, checking your own report or score is not an application, and FICO confirms that your own checks do not count.
Credit mix is the smallest category. In addition, you do not need one of every type of account, and taking out a loan you do not need just to add variety is a poor trade.
Why the same balance affects two people differently
Consider Taylor and Morgan, who each have a new $1,500 card balance, but different credit files:
| Detail | Taylor | Morgan |
|---|---|---|
| Total credit limits | $20,000 | $2,000 |
| Reported balance | $1,500 | $1,500 |
| Overall utilization | 7.5% | 75% |
| Credit history | Several older accounts | One new card |
| Recent applications | None | Two |
Hypothetical Money Behaves example. It does not predict either person’s score.
The balance is the same, yet it is only 7.5% of Taylor’s limits and 75% of Morgan’s. On top of that, Morgan has a shorter history and more recent applications. So the same $1,500 cannot affect both scores in the same way. That is exactly why rules like “a balance of this size costs this many points” are unreliable.
What your score does not include
Traditional credit scores only use information in your credit report, so a lot is left out. Therefore, according to FICO, they do not include your salary, job, employer or employment history. Your bank balance is not part of the report either, and paying with cash or a debit card does not build credit history.
Even so, income can still matter when you apply, because the lender may check whether you can afford the payment. However, rent, utility and subscription payments are a special case: they only count if they are reported and if the model being used includes them. This also explains why a high income does not guarantee a high score.
Check what may have changed your score
Use the interactive check below when your score moves and you are not sure why. In short, it connects common events with the part of the score they usually affect.
How to use it: tick every event that happened in the last month or two. Then, for each one, you will see the FICO category involved and a sensible next step. You can tick more than one option.
INTERACTIVE CHECK
Why did my score change?
Tick everything that happened in the last month or two. You will see which part of the score it usually affects and what to do next.
General guidance based on FICO’s published scoring categories. It cannot predict your exact score change, which depends on your full credit report and the model used.
How to improve your report instead of hacking the number
Unfortunately, no legitimate method can guarantee a specific increase by a specific date. Instead, a more reliable approach is to improve the information in your reports while protecting your budget:
- Pay every required amount on time. Calendar reminders, alerts or autopay can help, but check that autopay actually goes through.
- Keep card balances affordable. Lower utilization is generally better, and paying down expensive debt also saves interest. See Minimum Payments: Why $90 Feels Right.
- Review all three reports. The FTC explains that AnnualCreditReport.com is the official site for free reports. Then, if you find an error, dispute it with the bureau and the company that reported it.
- Apply for credit only with a purpose. After all, several applications add inquiries, new payments and possible fees. Before you apply, compare the real cost, as explained in How to Compare Loan Offers.
- Give it time. Account age and a record of on-time payments grow over months and years, so be wary of any offer that promises a fast, guaranteed score increase.
Common myths about credit scores
- “I have one official score.” In reality, several scores can be valid at the same time.
- “A higher income raises my score.” No. In fact, income is not part of a standard FICO Score.
- “Checking my own score lowers it.” Actually, your own checks are not counted. Only a lender’s hard inquiry after an application is counted, because that is a new request for credit.
- “I need to pay interest to build credit.” On the contrary, carrying a balance costs money without a special scoring benefit.
- “One action always changes my score by a known amount.” Not true, because the result depends on your full report and the model.
Check your understanding
A card issuer reports a higher balance, but you never missed a payment. Which category may change? Amounts owed, because the new balance can raise your utilization.
Someone applies for four cards in a short period. Which category is most affected? New credit, since recent applications and new accounts are counted there.
Two apps show different scores on the same day. Is one of them wrong? Not necessarily, because they may use different bureaus, models or update dates.
Next time your score changes, check this
- Pause before you act. A small change is usually a routine update, not an emergency.
- Compare like with like. Check whether you are looking at the same bureau, model and date as before.
- Look at the report, not just the number. Then find what actually changed and whether it is accurate.
- Ask if the fix helps your real finances. For example, never pay interest or open accounts just to move the score.
- Separate the score from yourself. After all, it predicts credit risk; it does not judge your worth.
ABOUT THE AUTHOR
Lorena founded Money Behaves. She is an economist and a psychology student who focuses on how people make money decisions: how they judge risk, react to percentages and read costs, and what happens when financial information gets complicated. She is not a licensed financial advisor, so every lesson relies on official U.S. sources and published research. See how we write and check our lessons.
Keep learning: How Credit Cards Work, How Credit Utilization Works and How a Debt Consolidation Loan Works.