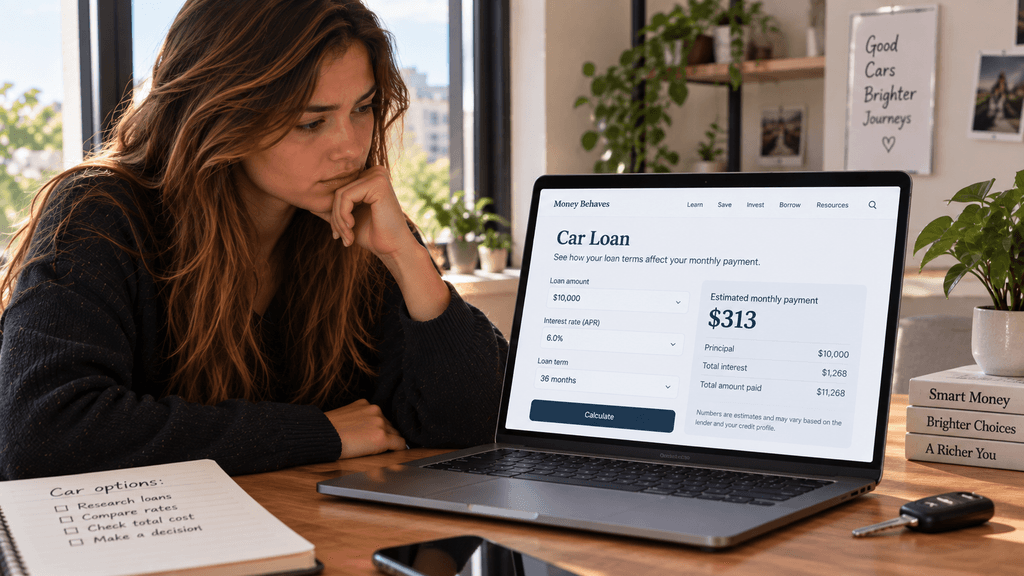
For example, imagine Ana needs $10,000 to replace her car. She does not have enough savings, so a lender offers her a loan with payments of about $313 a month. At first, the payment sounds manageable. Even so, it does not tell her how much she will repay in total, how long she will be in debt or what happens if she misses a payment.
In short, a loan turns one large expense today into a series of future payments. Of course, that can be very useful. However, it can also make an expensive purchase feel more affordable than it really is. In this lesson, we take a loan apart piece by piece, starting with a picture of how it shrinks over time.
A loan in one picture
Before the definitions, though, it helps to see what actually happens. The chart below shows how the balance of a loan goes down with each payment, and how much of everything you pay ends up as interest.
How to use it: enter a loan amount and an interest rate, then move the slider to change the term from 1 to 7 years. As a result, both charts update as you move it.
Notice two things as you move the slider. First, the line falls slowly at the start and faster at the end, because early payments go mostly to interest. Second, a longer term makes the orange slice bigger, since you pay interest for more months.
The five numbers in every loan
A loan offer can contain many details. Still, five numbers give you most of the picture, and each one answers a different question:
| Number | Question it answers | In Ana’s loan |
|---|---|---|
| Principal | How much are you borrowing? | $10,000 |
| Interest rate | What rate does the lender charge on what you owe? | 8% fixed |
| APR | What is the yearly cost, including certain fees? | 8%, with no fees |
| Term | How long will you be paying? | 36 months |
| Monthly payment | How much is due each month? | $313.36 |
Simplified example, because real offers can include fees, so the APR may be higher than the rate.
In particular, the APR deserves a closer look. According to the FDIC’s Truth in Lending guidance, it expresses the cost of credit as a yearly rate and can include charges beyond interest. So if a loan has fees, its APR will be higher than its interest rate, which is why you should compare APR with APR.
How a loan works from start to finish
- You apply. A bank, credit union, online lender or car dealer asks about your income, job, debts and credit history.
- The lender decides. Based on its own rules, it approves or declines, and offers a rate and term. Different lenders can make very different offers to the same person.
- You review the offer. Then you check the amount, rate, APR, payment, number of payments, fees and late-payment rules.
- You receive the money. It goes to your account, to a seller or straight into the purchase, and from that moment it is a debt.
- You repay on schedule. Each payment covers interest and part of the principal, until the balance reaches zero.
Generally, most personal loans, car loans and mortgages work this way. People call them installment loans, because you repay them through a set number of scheduled payments. As the FDIC explains, this is different from credit cards, where you can borrow again and again.
A complete example
Suppose Ana accepts a $10,000 loan at an 8% fixed rate for 36 months, with no fees. Then, over three years, she makes 36 payments of $313.36:
$313.36 × 36 ≈ $11,281 repaid in total
In other words, she borrowed $10,000 but repays about $11,281. Therefore, the difference, about $1,281, is the cost of borrowing under these terms.
What happens inside each payment
At first, Ana still owes almost the full $10,000, so more of each payment goes to interest. In her first month, for example, about $66.67 goes to interest and only $246.69 reduces what she owes. Later, as the balance shrinks, the interest part gets smaller and more of each payment goes to the principal. That is exactly why the line in the chart above starts flat and then drops faster.
MONEY TRAP
The deposit and the debt arrive together
When $10,000 lands in your bank account, at first it feels like your money just grew. In reality, your cash went up by $10,000, and your debts went up by the same amount at the same moment.
Then the monthly payment hides the rest of the story. “Only $203 a month” sounds easy, while five years of payments and $2,166 in interest stay out of sight. Research on car loans, which we cover in How to Compare Loan Offers, shows that many borrowers choose loans based on the payment, not the total cost.
So, instead, look at every loan in three ways at once: the payment, the number of months and the total you will repay.
Why a lower monthly payment can cost more
Now imagine a lender offers Ana two terms for the same $10,000 loan at 8%:
| Term | Monthly payment | Repaid in total | Interest paid |
|---|---|---|---|
| 36 months | $313.36 | $11,281 | $1,281 |
| 60 months | $202.76 | $12,166 | $2,166 |
Original Money Behaves calculation. Fixed rate, equal payments and no fees.
As a result, the five-year loan cuts the payment by more than $100 a month. However, Ana stays in debt two years longer and pays about $885 more in interest. Of course, the shortest term is not always best. After all, a payment that is too high can leave nothing for rent, food or emergencies. The goal is a payment you can manage, without ignoring what a longer term adds to the total.
Secured and unsecured loans
Some loans also depend on something you own. For example, a secured loan, such as a mortgage or a car loan, uses your home or car as collateral, so the lender can take it if you stop paying. An unsecured loan, such as most personal loans, does not use a specific asset. Still, “unsecured” does not mean optional: missed payments can lead to fees, collections and damage to your credit. We cover the difference in detail in Secured vs. Unsecured Loans.
Fixed rates, variable rates and fees
First, a fixed rate stays the same for the whole term, so your payment is predictable. By contrast, a variable rate can change based on the terms in your agreement. Also, a low starting rate may look attractive, but you need to know when it can change and how high it can go.
Fees can change the deal, too. For example, a 5% origination fee on a $10,000 loan is $500. So if the lender takes it from the money you receive, you get only $9,500, while you still owe $10,000. In addition, other possible costs include late fees, returned-payment fees, optional add-ons and, in some loans, a prepayment penalty.
What happens if you miss a payment
Unfortunately, missing a payment does not make the debt disappear. Instead, it can bring a late fee, extra interest and a negative mark on your credit report, as explained in Credit Score Explained. Also, with a secured loan, it can eventually put the collateral at risk.
If you think you will struggle with a payment, contact the lender before the due date. Sometimes, lenders offer temporary arrangements, although these are not guaranteed and can change the total cost. Also, keep an eye on automatic payments, since a withdrawal from an account without enough money can create a new problem.
Before you sign, check these three numbers
Whenever you look at a loan, write down three numbers next to each other: the monthly payment, the number of months and the total you will repay. Together, then, they give you the full picture that the payment alone hides. To go further, compare several offers with the method in How to Compare Loan Offers, or, if you are borrowing to pay off cards, read How a Debt Consolidation Loan Works.
ABOUT THE AUTHOR
Lorena founded Money Behaves. She is an economist and a psychology student who focuses on how people make money decisions: how they judge risk, react to percentages and read costs, and what happens when financial information gets complicated. She is not a licensed financial advisor, so every lesson relies on official U.S. sources and published research. See how we write and check our lessons.